
Overview
This use case models counterparty credit risk and Credit Valuation Adjustment (CVA) for a portfolio of derivative exposures. The objective is to quantify the economic cost of the possibility that a counterparty defaults before all contractual cash flows are settled. Rather than treating derivatives only at their risk-free market value, the workflow adjusts valuation for expected exposure, probability of default and loss given default, producing a counterparty-level CVA measure.
CVA is one of the central links between market risk and credit risk. A position may be profitable from a market perspective but still carry material counterparty loss potential if the exposure is large and the counterparty credit quality is weak. By decomposing CVA by counterparty, the analysis shows where the portfolio's credit-adjusted valuation risk is concentrated and where limits, collateral or hedging actions may be required.
Business relevance
- Quantify the expected valuation loss caused by counterparty default risk.
- Identify which counterparties contribute most to portfolio CVA.
- Support counterparty limits, collateral policy and credit-risk pricing.
- Integrate market exposure and credit quality into a single valuation adjustment.
- Provide a transparent input for XVA reporting, capital allocation and risk committees.
Solution
The solution is to use counterparty-level CVA as a prioritisation tool for credit-adjusted valuation and exposure management. Figure 1 makes concentration immediately visible. Counterparties 4 and 5 generate by far the largest CVA values, at approximately 17,081 and 11,487 notional units respectively, while Counterparty 3 contributes only around 1,289. This means the economic cost of counterparty risk is highly uneven across the portfolio and should not be managed with a uniform limit or collateral policy.
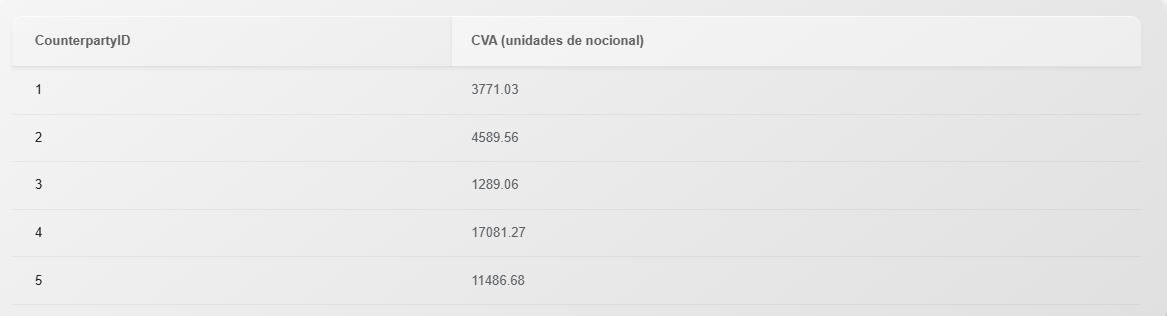
The CVA ranking can be translated directly into action. High-CVA counterparties should be reviewed first for exposure reduction, tighter trading limits, additional collateral, netting opportunities or credit hedges. Lower-CVA counterparties require less immediate intervention because either their expected exposure, default probability or loss severity is materially smaller. This creates a risk-based allocation of management attention rather than a purely notional-based one.
The chart therefore connects model output with portfolio decisions: it identifies where credit-adjusted valuation losses are concentrated and provides a defensible basis for pricing, limit setting and XVA governance. As market exposures and counterparty credit quality change, the same framework can be rerun to monitor whether CVA concentration is increasing and whether previously acceptable counterparties are becoming material sources of risk.