
Overview
This use case applies portfolio optimisation techniques to a fixed-income universe, using government bonds with different maturities to construct allocations that balance expected return and interest-rate risk. The workflow compares instruments such as 10-year, 20-year and 30-year U.S. Treasuries through their historical mean returns and volatility, creating the inputs required for an optimised bond portfolio.
The key challenge in fixed income is that a higher expected return is usually accompanied by greater sensitivity to interest-rate movements and therefore higher price volatility. Optimisation makes that trade-off explicit, allowing an investor to choose an allocation that fits a specific risk budget instead of simply selecting the bond with the highest standalone return.
Business relevance
- Compare long-duration government bonds using expected return and volatility on a consistent basis.
- Construct fixed-income portfolios that match a defined risk budget or return target.
- Avoid concentrating the portfolio in the highest-yielding maturity without considering its additional volatility.
- Support duration allocation, strategic fixed-income positioning and portfolio rebalancing.
- Provide a transparent quantitative basis for selecting between 10Y, 20Y and 30Y Treasury exposures.
Solution
The solution is to use the return-volatility profile in Figure 1 as the starting point for an optimised maturity allocation. The 10-year Treasury has the lowest volatility, around 2.5%, and also the lowest mean return, around 0.69%. The 20-year Treasury offers the highest mean return, around 0.79%, but its volatility rises to roughly 3.78%. The 30-year bond carries almost the same volatility as the 20-year bond, at about 3.72%, while its mean return is lower, around 0.73%.
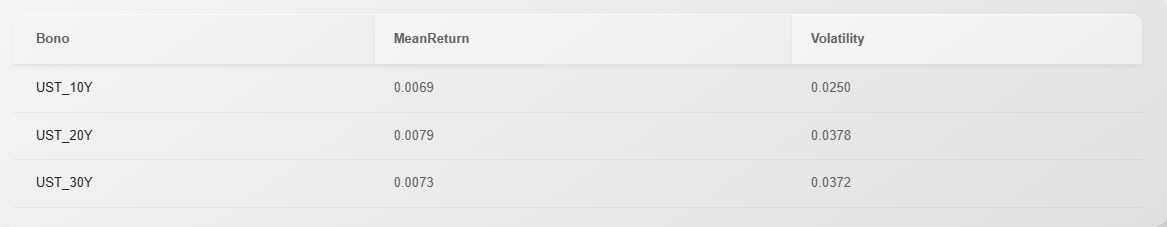
Those numbers immediately reveal that the longest maturity is not automatically the most attractive instrument. On a standalone basis, the 20-year Treasury offers a stronger return for roughly the same volatility as the 30-year bond, while the 10-year Treasury remains the defensive anchor of the set. An optimiser can therefore combine the lower-risk 10Y exposure with the higher-return 20Y exposure and use the 30Y only when its covariance or duration characteristics improve the portfolio-level result.
The practical output is a maturity mix tailored to the investor's objective. A conservative mandate would allocate more heavily to the 10Y bond; a return-seeking mandate could increase the 20Y weight; and an ALM or duration-targeted portfolio could introduce 30Y exposure when long-duration cash-flow matching is valuable. The table therefore becomes the quantitative basis for deciding how much return the investor is receiving for each additional unit of fixed-income volatility.